HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS: THE KALAMAZOO RAPID RESCORE SECRET!
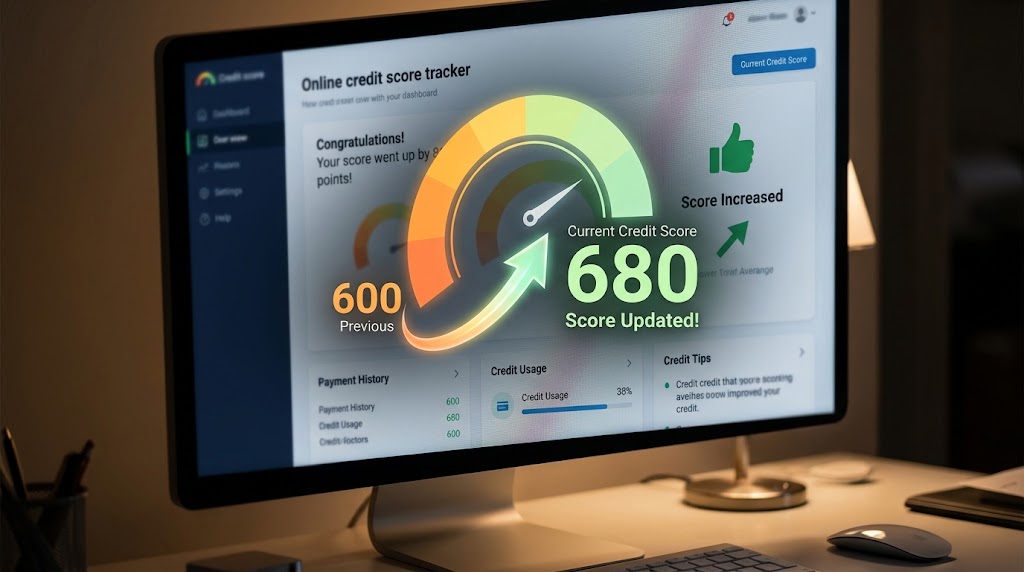 Did you pull your free credit score on a mobile app, see a solid 680, and then watch a mortgage lender pull a 635 that bumps your interest rate or private mortgage insurance (PMI)?
Yesterday, a frustrated home buyer walked into my office after looking at houses in Portage. They wanted to make an offer by Friday.
Their middle credit score sat at 618. That number left them just two points shy of the critical 620 tier for Conventional financing, which forced them toward higher monthly fees.
The buyer looked at me and asked, “Jeremy, does it take months of waiting for credit card companies to report my payments before my mortgage score climbs?”
I told them straight up: “ABSOLUTELY NOT! You do not have to wait 30 to 60 days for monthly billing cycles to roll over! We can update your credit report directly with the credit bureaus in 3 TO 5 BUSINESS DAYS USING A RAPID RESCORE!”
Consumer apps show VantageScores, which ignore the strict tri-merge FICO models (FICO 2, 4, and 5) that mortgage underwriters actually use. When you pay down a credit card balance on your own, the credit card company only reports that new balance once a month on your statement closing date.
If you find your dream home in Kalamazoo County today, you do not have 45 days to wait for automated bureau updates.
Think of a rapid rescore like filing an expedited IFR flight plan clearance directly with Kalamazoo Air Traffic Control. When bad weather forces you to alter your route, you do not sit idling on the taxiway for an hour hoping the control tower notices your transponder. You call departure control directly, transmit your verified flight data, secure your direct clearance, and climb straight into smooth air!
Here is how a rapid rescore changes your purchasing power on a $275,000 home in Kalamazoo County:
| Credit Score Tier | Mortgage Financing Impact | Monthly PMI Cost ($275,000 Home) | Interest Rate Impact |
| 618 (Before Rescore) | Blocked from Conventional; forced into FHA or higher pricing | ~$185 / month | Higher baseline rate |
| 642 (After 5-Day Rescore!) | Unlocks Conventional financing with lower loan-level fees! | ~$95 / month | Slashes your rate & saves $90/mo in PMI! |
| 740+ (Top Tier) | Maximum pricing discounts across all programs | Lowest available PMI (~$45/mo) | Lowest available interest rates! |
HOW RAPID RESCORING WORKS
You cannot purchase a rapid rescore on your own. Credit bureaus only offer this direct pipeline to licensed mortgage lenders during an active mortgage application.
Here is the exact step-by-step process we run:
-
We Run What-If Credit Simulations: We plug your tri-merge credit report into our credit simulator software. The software identifies the exact dollar amounts to pay down on specific credit cards to generate maximum point gains.
-
You Pay Down the Target Balance: You pay down the balance (for example, paying $400 on a card that sits at 85% credit utilization to drop it below 29%).
-
We Gather Direct Proof: You secure an official balance update letter or zero-balance statement directly from the creditor.
-
We Transmit Direct Bureau Updates: Our team submits that certified documentation straight to Equifax, Experian, and TransUnion.
-
Your Score Updates in 3 to 5 Days: The credit bureaus re-calculate your score within days instead of months!
REAL KALAMAZOO RESULTS
Yesterday, our simulation showed that paying down $620 across two retail cards would drop that Portage buyer’s utilization ratio under 30%.
Our buyer paid the cards online, downloaded the updated payment confirmation letters, and handed them to our team.
We submitted the rapid rescore package immediately. By Friday, their middle credit score will climb from 618 to 645! That 27-point jump unlocks Conventional financing, saves them over $90 every month on private mortgage insurance, and protects their offer on the Portage home!
Never let an outdated credit report dictate your interest rate or delay your home purchase. Let a local mortgage team analyze your credit profile, execute targeted point gains, and clear you for takeoff!
Ready to see how fast you can optimize your mortgage credit score in West Michigan? Reach out today, call our team at 269.360.7109, and let us build your custom mortgage flight plan!

Latest Blog Post
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS: THE KALAMAZOO RAPID RESCORE SECRET!
Did you pull your free credit score on a mobile app, see a solid 680, and then watch a mortgage lender pull a 635 that bumps your interest rate or private mortgage insurance (PMI)?
Yesterday, a frustrated home buyer walked into my office after looking at houses in Portage. They wanted to make an offer by Friday.
Their middle credit score sat at 618. That number left them just two points shy of the critical 620 tier for Conventional financing, which forced them toward higher monthly fees.