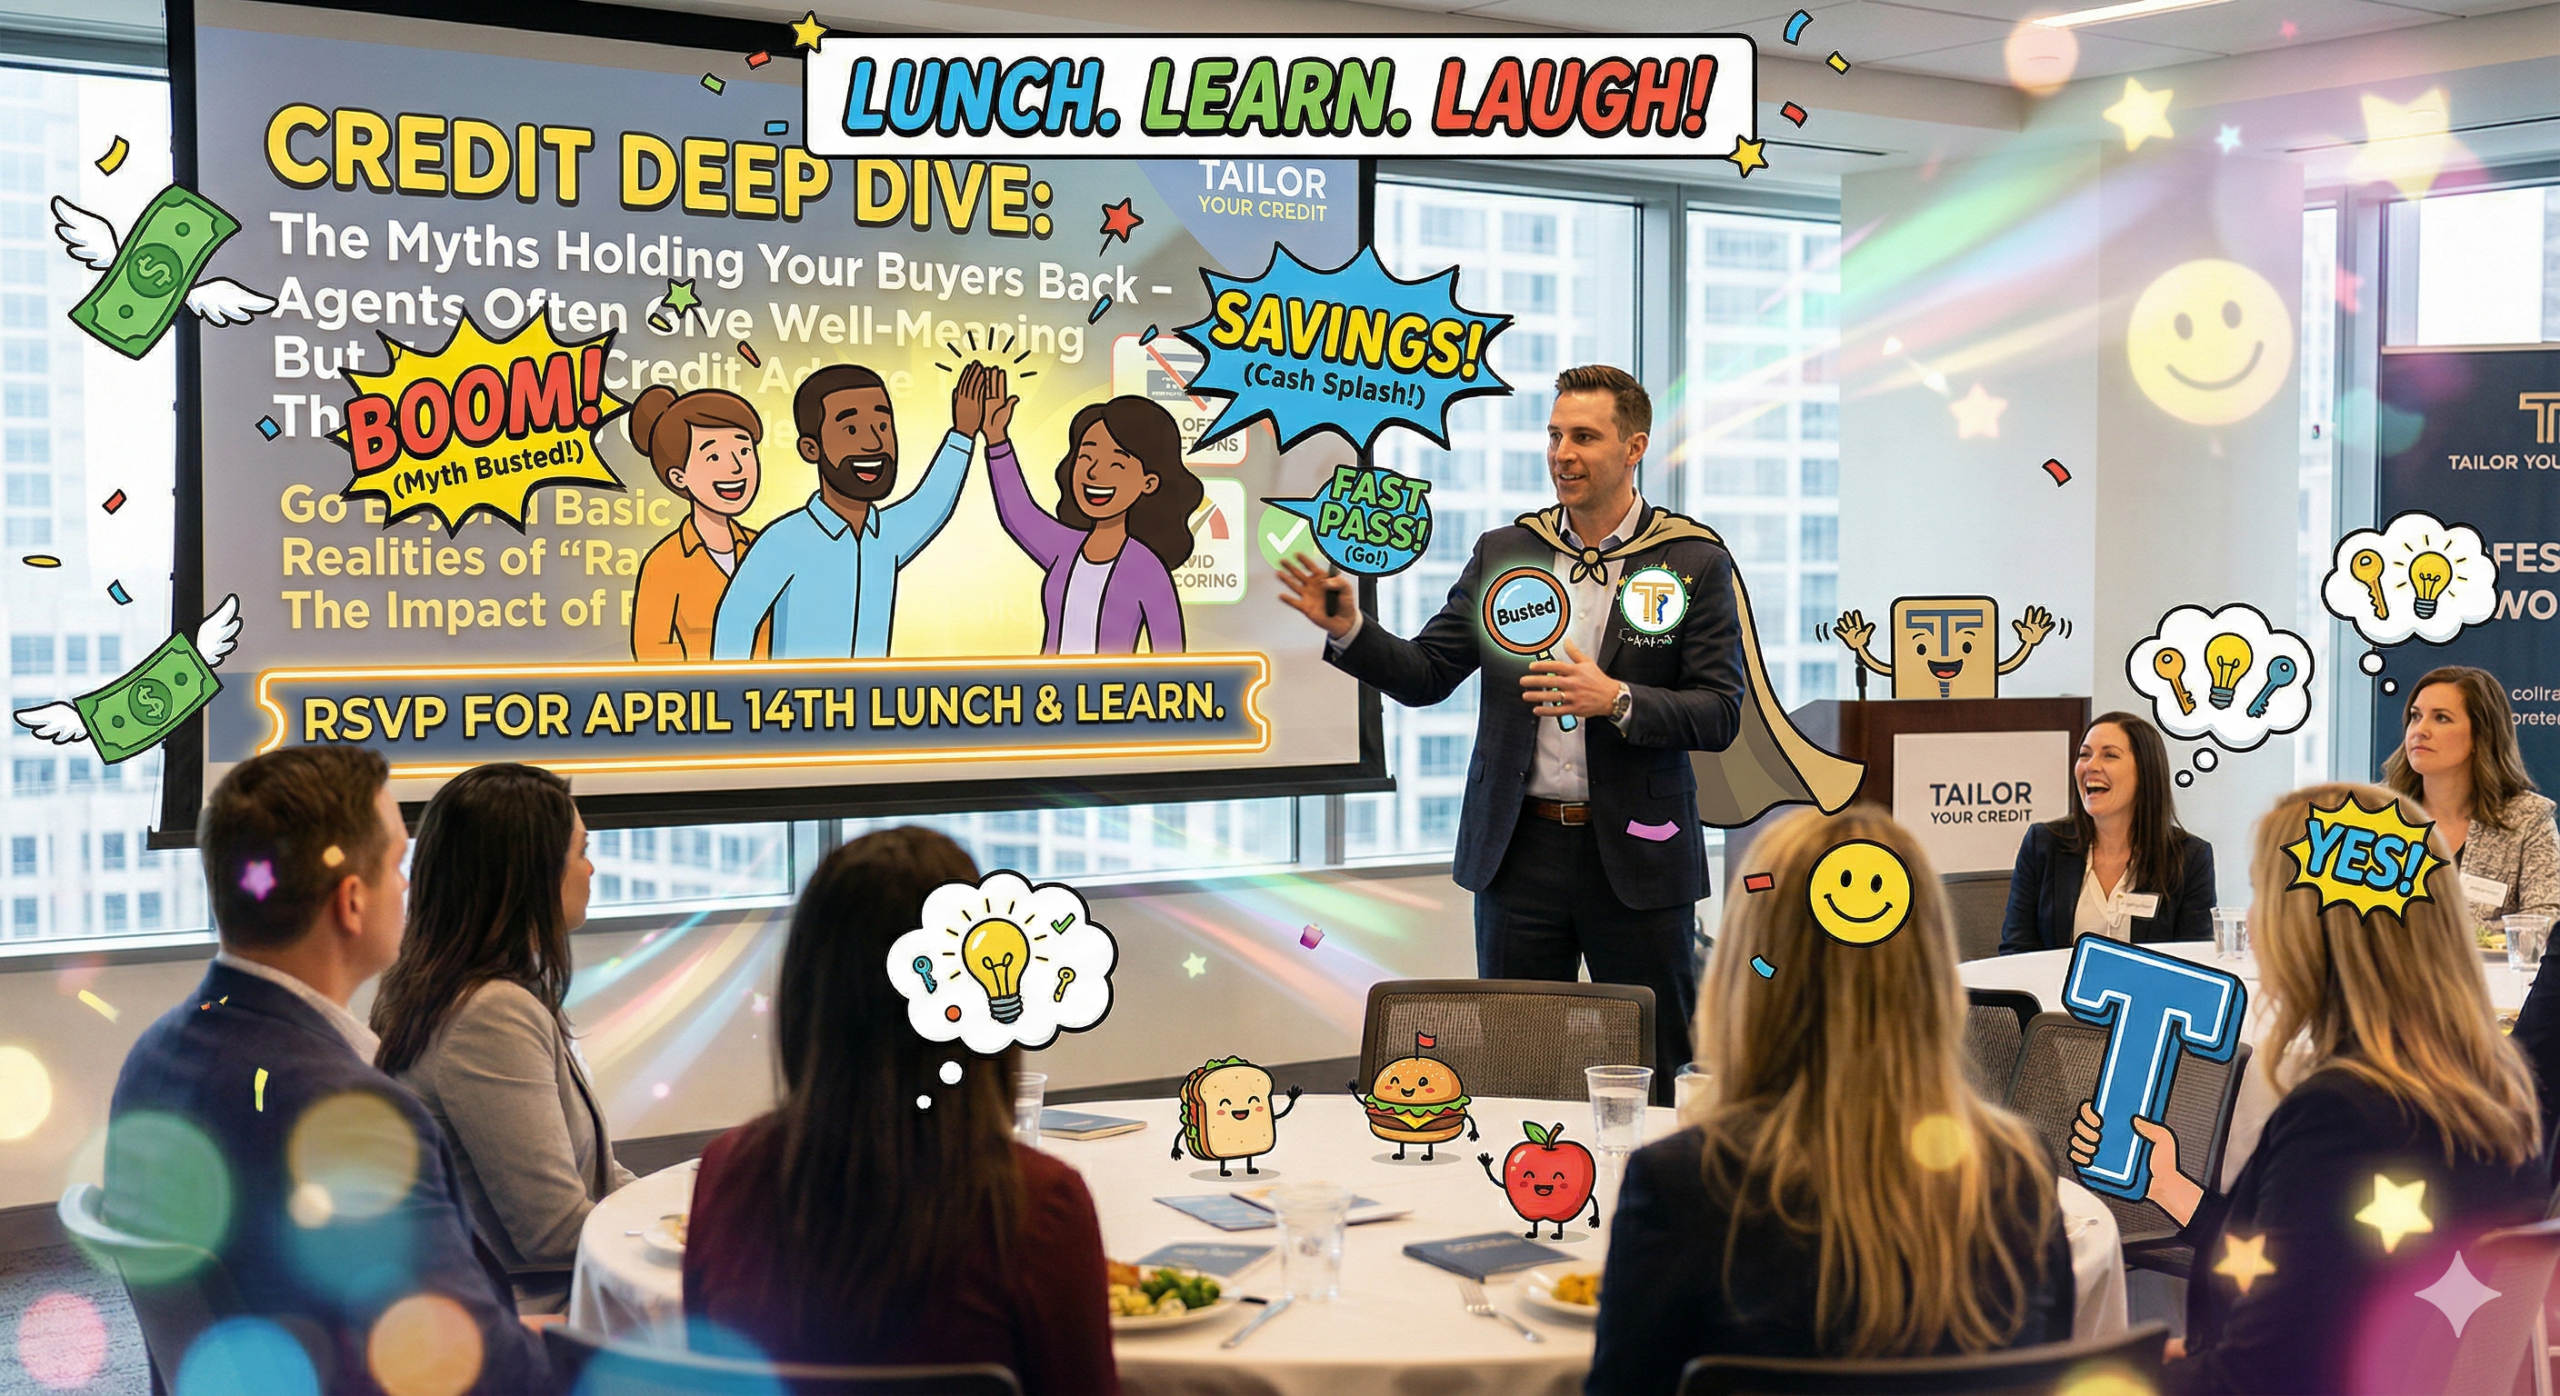
Credit Deep Dive: The Myths Holding Buyers Back
Is Your Best Credit Advice Killing Your Deals?
 You want to be the hero for your clients. You tell them to pay off those old collections and close those dusty credit cards to “clean things up” before they apply for a mortgage. It sounds like a great plan, right? Wrong.
In the world of mortgage lending, “common sense” credit advice is often a deal-killer. One wrong move can tank a 700 score to a 640 overnight, turning a “Clear to Close” into a “Denial”.
The “Laundromat” Reality of Credit
Think of a credit score like a pile of laundry. If you try to wash a 5-year-old stained shirt (an old collection) with your fresh white towels (your current good habits), the old dye bleeds. Paying an old debt can actually reset the clock on the “Date of Last Activity,” making a stale mistake look like brand-new bad news to the algorithm.
Stop letting well-meaning advice stand between your buyers and their new keys.
Join Us: Credit Deep Dive Lunch & Learn
DATE: April 14th
TOPIC: The Myths Holding Buyers Back
What we are covering:
-
The “Reset” Trap: Why paying off old collections often hurts more than it helps.
-
The Secret Weapon: How “Rapid Rescoring” can fix a score in 3 to 5 days instead of 30.
-
Bucket math: Why closing old cards actually shrinks your client’s borrowing power.
-
The 911 Checklist: What your buyers must NOT touch before closing day.
The Math of the “Almost” Buyer
| Credit Score | Monthly Payment Impact | 30-Year Waste |
| 760+ (The Goal) | $2,500/mo | $0 |
| 615 (The “Almost”) | $2,750/mo | $90,000 |
Don’t let your clients burn $90,000 because of a myth. Let’s get them the best rates and get you more closed files.
SIGN UP TODAY!
LIVE EVENT – NEW LOCATION!!!
Date: Tuesday, April 14th, 2026
Time: 12:00 – 1:00
Location: Treadstone Mortgage – 616 W. Centre Ave, Portage, MI 49024 <——–
Limited Seating. RSVP required. Lunch will be provided.

Latest Blog Post
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS: THE KALAMAZOO RAPID RESCORE SECRET!
 Did you pull your free credit score on a mobile app, see a solid 680, and then watch a mortgage lender pull a 635 that bumps your interest rate or private mortgage insurance (PMI)?
Yesterday, a frustrated home buyer walked into my office after looking at houses in Portage. They wanted to make an offer by Friday.
Their middle credit score sat at 618. That number left them just two points shy of the critical 620 tier for Conventional financing, which forced them toward higher monthly fees.