Rural Development Turn Times
When it comes to getting a mortgage timing is everything. “When are we going to close?” is the question we get asked more often than anything else. The Real Estate Agents, buyers, and sellers all need to know when closing is going to occur. One of the biggest challenges with Rural Development financing is closing time frames.
The Michigan RD offices current turn times:
5-10 days Business Day Turn Times
* We try to keep this as up to date as possible email us if you need more info
 With RD the basic process works as follows:
- Offer accepted
- Start loan process & order the appraisal
- Appraisal received (after 1 – 2 weeks)
- File goes to underwriting
- Once files back from underwriting it is sent to RD for there approval.
- This is where we sometimes get caught in traffic. Sometimes RD turns files in a matter of days, sometimes weeks or even months. The file will literally sit up there in a stack and they review them in the order received. They get to it when they get to it. Current turn times are posted above.
- File comes back from RD, our underwriter clears it for closing
- Closing scheduled a few days later.
So what’s all that mean? Basically if a normal loan takes 30 – 45 days to close, take whatever the above turn time is for RD and add it to it. Generally speaking you will see those RD turn times very fast in the beginning of the year, then as spring hits and things pick up they get more and more backed up, by November/December they are starting to catch up again and the cycle continues.
Although RD approval is more of a formality it still is a requirement that the RD fairies bless the file prior to closing, so we are often stuck waiting.

Latest Blog Post
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS
HOW TO BOOST YOUR MORTGAGE CREDIT SCORE IN 3 TO 5 DAYS: THE KALAMAZOO RAPID RESCORE SECRET!
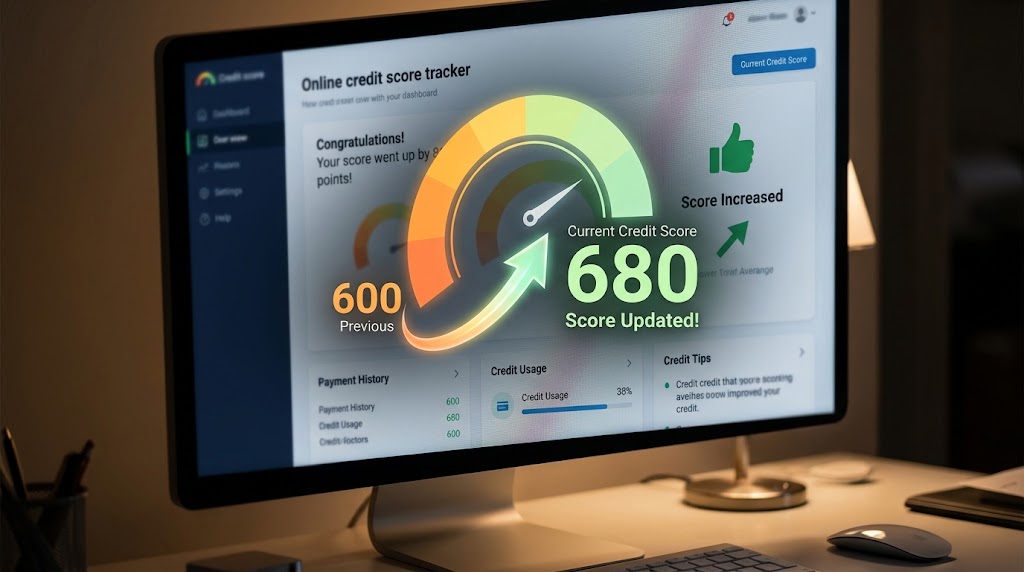 Did you pull your free credit score on a mobile app, see a solid 680, and then watch a mortgage lender pull a 635 that bumps your interest rate or private mortgage insurance (PMI)?
Yesterday, a frustrated home buyer walked into my office after looking at houses in Portage. They wanted to make an offer by Friday.
Their middle credit score sat at 618. That number left them just two points shy of the critical 620 tier for Conventional financing, which forced them toward higher monthly fees.