HOW TO BUY A HOME USING BANK STATEMENTS INSTEAD OF TAX RETURNS!
SELF-EMPLOYED IN KALAMAZOO?
HOW TO BUY A HOME USING BANK STATEMENTS INSTEAD OF TAX RETURNS!
Did you build a thriving business in Kalamazoo, Portage, or Texas Township, write off legitimate business expenses on your IRS tax returns to lower your tax bill, and then hear a traditional bank tell you that you do not earn enough income to buy a house?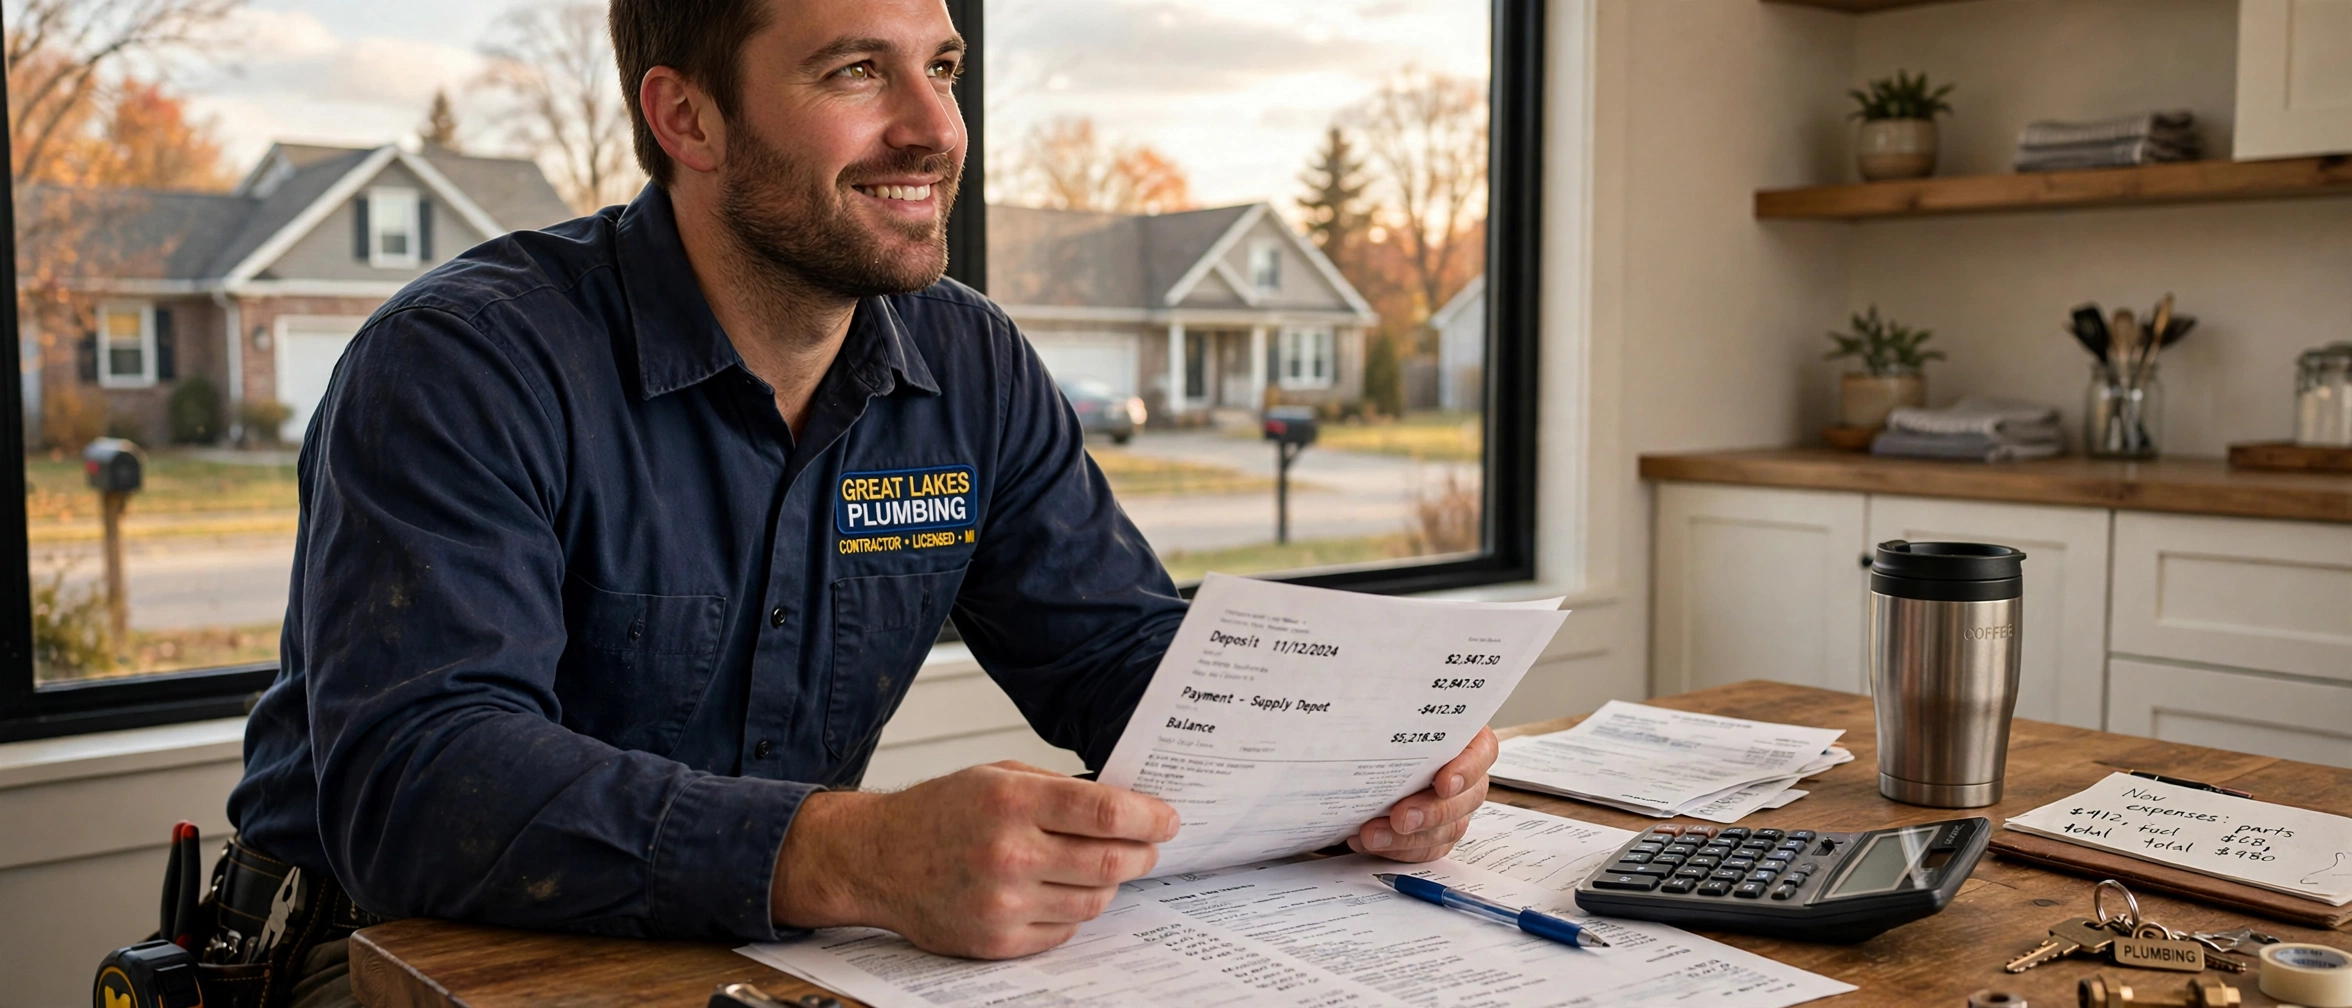
Yesterday afternoon, a sharp local plumbing contractor walked into my Portage office feeling completely frustrated.
Over the past week, they toured an updated four-bedroom home near Texas Corners listed at $340,000.
Their business deposited over $24,000 every single month into their business checking account.
However, after their CPA deducted truck depreciation, fuel, equipment, and supply write-offs on Schedule C, their net taxable income on paper dropped to just $46,000 a year.
An out-of-state online lender took one glance at their tax returns and rejected their loan application on the spot.
The buyer sat across my desk and asked, “Jeremy, do business owners in Kalamazoo County really have to overpay the IRS for two straight years just to prove we can afford a mortgage?”
I looked them right in the eye and said: “ABSOLUTELY NOT! You run a real business with real cash flow, and you do not have to penalize yourself at tax time just to buy a house! We qualify self-employed buyers across Southwest Michigan every month using a 12-MONTH OR 24-MONTH BANK STATEMENT MORTGAGE!”
Traditional Fannie Mae and Freddie Mac underwriters look strictly at the bottom line of your IRS Form 1040 after every business deduction.
A BANK STATEMENT LOAN skips your tax returns completely!
Instead, our underwriters analyze 12 or 24 consecutive months of your actual business or personal bank deposits to calculate your true monthly cash flow!
Think of a bank statement mortgage like checking the real-time hydraulic pressure gauge on a heavy-duty service crane instead of reading last year’s maintenance receipt book. A tax return only shows what remained after you wrote off your tools and fuel. Your bank statements measure the actual, live horsepower pumping through your business every single month so you can lift your family straight into your next home!
Look at how a 12-Month Bank Statement Loan compares against a traditional tax-return mortgage for a self-employed buyer in Kalamazoo County right now:
| Mortgage Qualification Feature | Traditional Conventional Loan | 12-Month / 24-Month Bank Statement Loan | Your Direct Bottom-Line Advantage |
|---|---|---|---|
| IRS Tax Returns & W-2s Required? | Mandatory (2 full years of 1040s & K-1s) | ZERO TAX RETURNS REQUIRED! | Keep your legitimate CPA tax write-offs! |
| How Underwriters Calculate Income | Net taxable income after all deductions | Consistent monthly bank deposits minus expense factor | Unlocks massive true borrowing power! |
| Minimum Self-Employment History | 2 years | 2 years (1 year allowed with strong industry background) | Works for contractors, Realtors, & shop owners! |
| Minimum Credit Score Baseline | 620 minimum | 640 to 660 baseline | Flexible underwriting for business owners! |
| Minimum Down Payment | 3% to 5% | 10% Down Payment | Avoids monthly PMI charges! |
| Kalamazoo County Loan Limits | Capped at $832,750 | Up to $2,000,000+! | Covers move-up and lakefront homes across SW MI! |
HOW EXPENSE FACTORS TURN DEPOSITS INTO QUALIFYING INCOME
When you submit 12 months of business bank statements, underwriters know your company pays overhead costs.
Instead of forcing you to prove every receipt, we apply a simple, predictable EXPENSE FACTOR:
Standard 50% Expense Ratio: On a $24,000 monthly deposit stream, the underwriter applies a flat 50% expense factor and credits you with $12,000 PER MONTH ($144,000 PER YEAR) in qualifying income!
Custom CPA Expense Letter (As Low as 10% to 15%): If you operate a low-overhead service business—such as consulting, real estate, software, or solo contracting—your CPA can sign a brief one-page letter confirming your actual business overhead sits at 15% or 20%. That pushes your qualifying income even higher!
3 QUICK TIPS TO PREPARE YOUR BANK STATEMENTS BEFORE APPLYING
If you own a business in Kalamazoo, Portage, Richland, or Schoolcraft and plan to buy a home soon, follow these three simple habits:
- Keep Business and Personal Accounts Separate: Route all customer payments and business expenses through one dedicated business checking account so the deposit trail stays crystal clear.
- Avoid Non-Sufficient Funds (NSF) Fees: Underwriters review your statements for clean cash management, so keep a healthy buffer in your operating account.
- Document Large Non-Business Transfers: If you move money from a personal savings account into business checking, keep a copy of the transfer slip so the underwriter excludes it cleanly without questions.
HOW WE CLEARED THAT TEXAS CORNERS CONTRACTOR YESTERDAY
Yesterday afternoon, our team reviewed 12 months of business checking statements for that local plumbing contractor.
His deposits averaged $24,500 per month.
With a brief expense verification letter from his CPA confirming a 35% operating overhead, we verified $15,925 IN QUALIFYING MONTHLY INCOME—more than four times what his tax returns showed on paper!
We issued an airtight pre-approval letter for his $340,000 Texas Corners purchase, called the listing agent directly, and helped him lock down the home!
Stop letting smart tax write-offs block you from buying the home your family deserves. Use your real business cash flow, skip the tax-return headache, and buy your next Southwest Michigan home with confidence!
Ready to see how much home your business bank deposits qualify you for in Kalamazoo County? Reach out today, call our team at 269.360.7109, and let us build your custom mortgage strategy!

Latest Blog Post
HOW TO BUY A HOME USING BANK STATEMENTS INSTEAD OF TAX RETURNS!
SELF-EMPLOYED IN KALAMAZOO?
HOW TO BUY A HOME USING BANK STATEMENTS INSTEAD OF TAX RETURNS!
Did you build a thriving business in Kalamazoo, Portage, or Texas Township, write off legitimate business expenses on your IRS tax returns to lower your tax bill, and then hear a traditional bank tell you that you do not earn enough income to buy a house?