Need Your Help Building “The Bar”!
YTD Dollar Amount Of Repairs Completed: $167,481.10
It seems that now days appraiser required repairs are almost the norm. Looking back at the loans my team closed so far in 2014 over 40% had one repair or another required by the appraiser. There is a misnomer out that that conventional financing is some how shielded from required repairs, that simply not true. Now these transaction don’t have to fall apart simply because there is a busted window or missing toilet, in fact I don’t think any transaction should fall apart because of appraiser required repairs. We have a number of options when it comes to seeing these transactions through to closing. You can read all those options here. I will say setting up a repair escrow is by far the most popular option. In fact, 95% of the borrowers that ran into repair issues chose to deal with those repairs using a repair escrow.
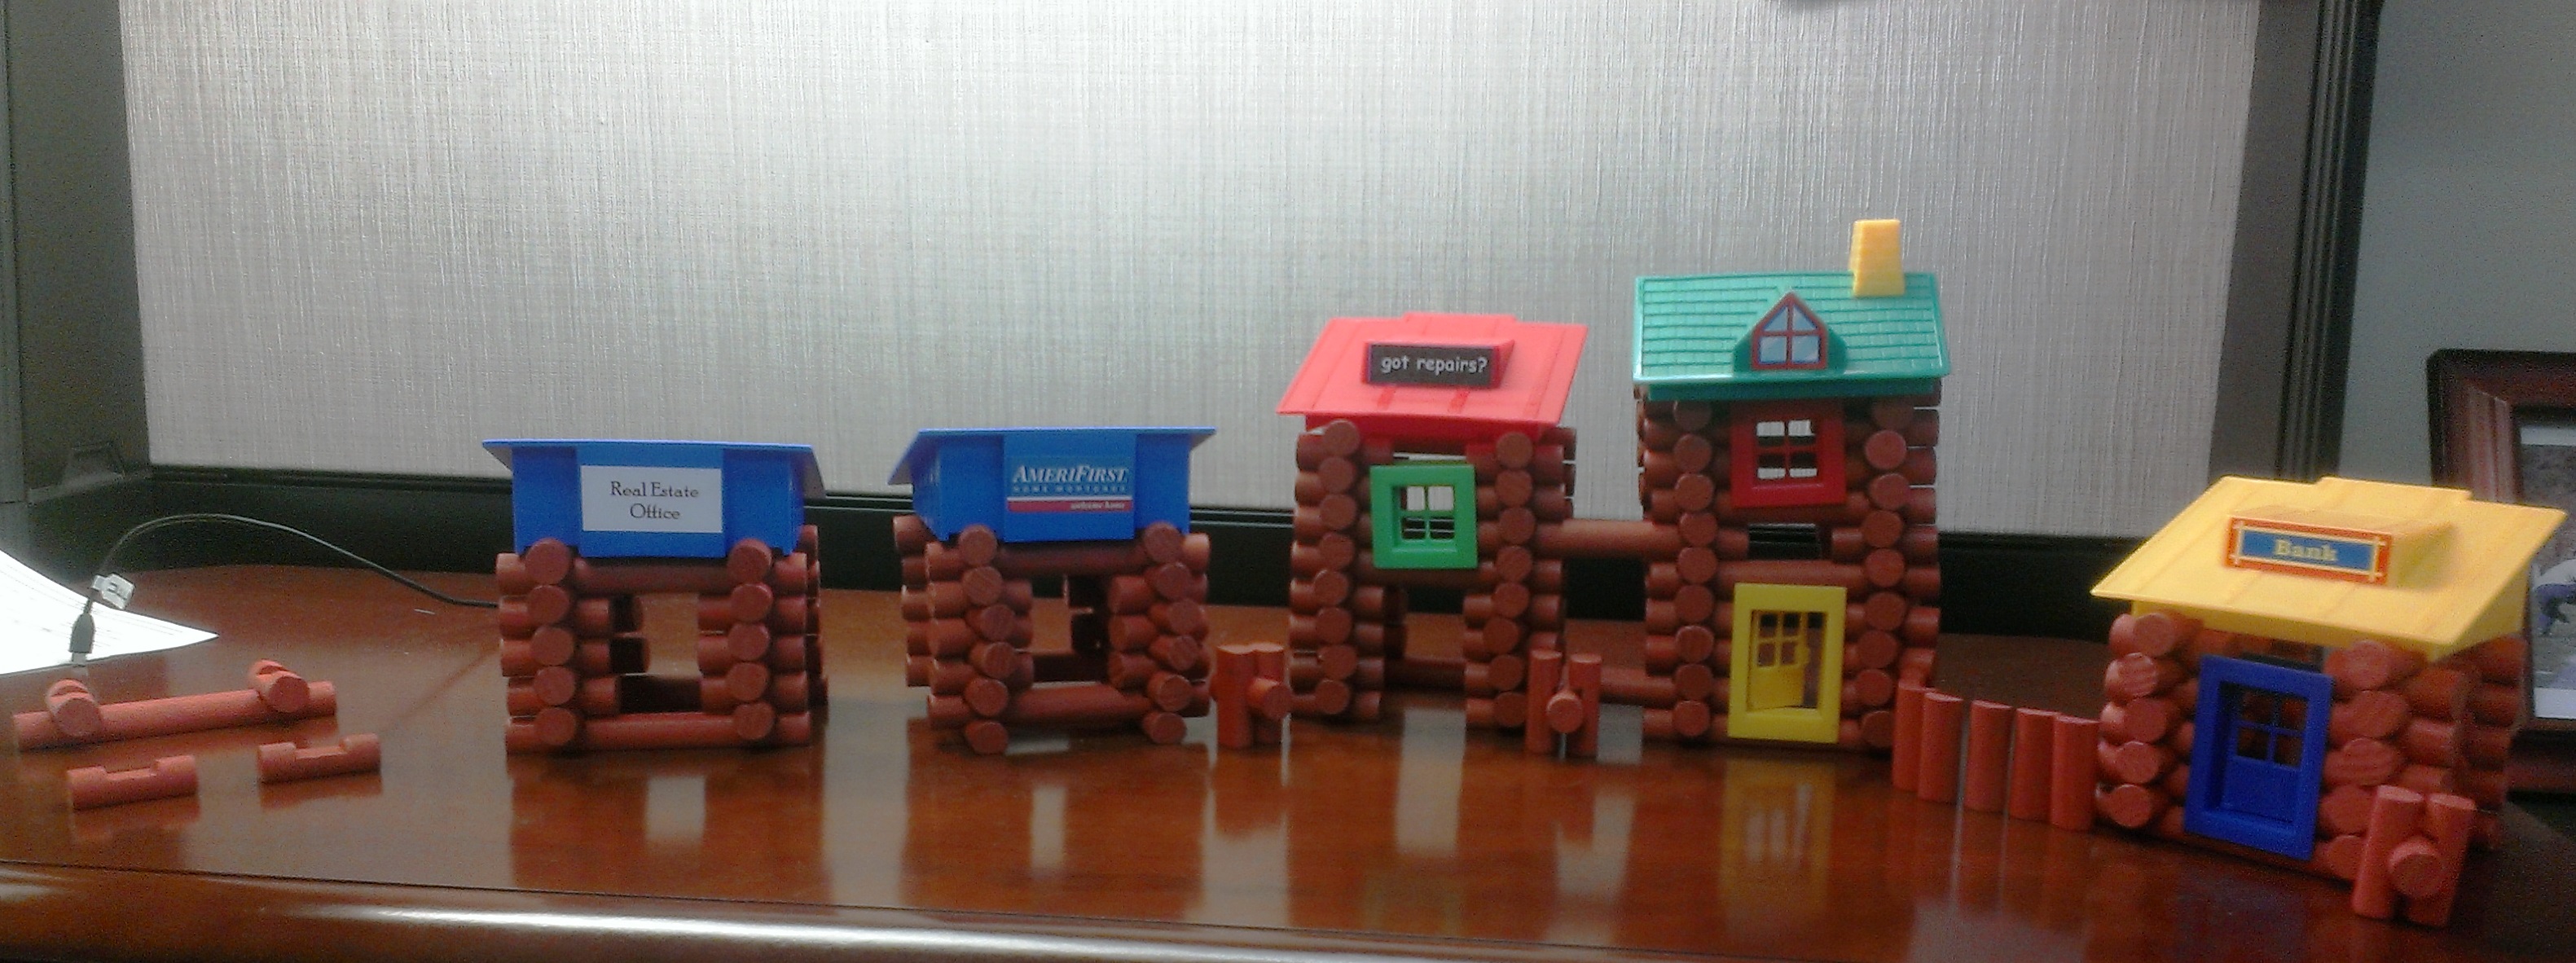
If you have been following my previous post my team is playing a little game building a log home tracking how many loans we gets closed that have repairs.
Each block on the house represents $500 worth of repairs we escrowed for and had completed after closing.
With October over we only have 2 months left to complete the most important building “The Bar” slated to be constructed right next to the Real Estate Office. I need your help to make this happen. If you have any repairs that need to be completed after closing give me a call!

Latest Blog Post
S.O.S. SAVE OUR SALE
S.O.S. SAVE OUR SALE: WHAT TO DO WHEN YOUR LENDER STALLS WEEKS BEFORE CLOSING!
 Did your mortgage lender suddenly go radio silent, request the same bank statement for the fourth time, or drop a last-minute loan denial right before your scheduled closing date?
Yesterday, a panicked real estate agent called my office from Portage. Their buyer had been under contract for three weeks on a home near Milwood. The closing date sat just nine days away.
Out of nowhere, the buyer’s out-of-state call-center lender issued a denial letter. The call-center underwriter miscalculated self-employment write-offs, panicked over an unpermitted porch repair on the appraisal, and threw the entire transaction into the trash can.